Home / Buy / Cost of Waiting Calculator
Free tool for Eau Claire home buyers
Cost of Waiting to Buy a Home Calculator
Thinking about waiting for a better time to buy? Use this cost of waiting to buy a home calculator to see what staying on the sidelines could cost you over the life of your loan. Move the sliders or type your own numbers.
Your numbers
Example rate only, not a quote. Enter the rate a lender has quoted you.
What waiting adds up to
Extra you would pay by waiting
to buy the same home later
Buy now
per month, principal and interest
If you wait
per month, principal and interest
Want to run your real numbers?
AJ Minaker | Summit Real Estate Group | REAL Broker
Quick Answer: Is It Cheaper to Buy Now or Wait?
It depends on how far rates fall compared with how much prices rise while you wait. On a $325,000 home with 10% down at 6.75%, if prices rise 4% over the next year, rates would need to drop below about 6.35% before waiting comes out ahead over a 30-year loan.
Worked Example: Waiting 12 Months on a $325,000 Eau Claire Home
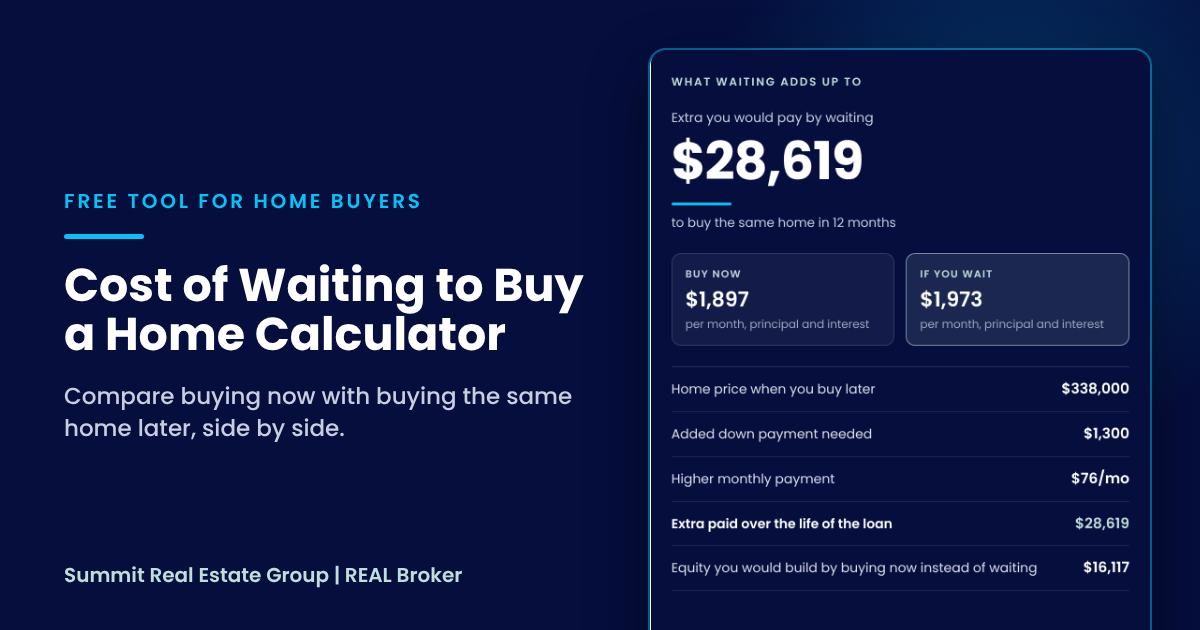
Here is what the cost of waiting to buy a home looks like using the calculator's default numbers: a $325,000 home, 10% down, a 30-year loan at 6.75% today and 4% yearly appreciation. After 12 months the same home costs about $338,000, which takes $1,300 more down payment. The table shows how the result changes depending on where rates are when you buy.
| Rate when you buy later | Monthly payment | Change per month | Extra paid over the loan |
|---|---|---|---|
| Buy now at 6.75% | $1,897 | none | none |
| Wait, rate stays 6.75% | $1,973 | +$76 | $28,619 |
| Wait, rate falls to 6.50% | $1,923 | +$26 | $10,517 |
| Wait, rate falls to 6.25% | $1,873 | minus $24 | about $7,400 less |
Principal and interest only. Example rates for illustration, not a quote or an offer of credit. The APR is not shown.
Buying now would also build about $16,100 of equity during those 12 months through appreciation and principal paydown. If rates fall after you buy, refinancing may be an option, but it has its own costs and is never guaranteed.
How the Cost of Waiting Calculator Works
The cost of waiting comes from two things that can change while you wait: the price of the home and the interest rate on your loan. The calculator shows its work:
- Home price when you buy later. Today's price grown by the yearly appreciation you enter.
- Added down payment. The same down payment percentage on a higher price takes more cash.
- Monthly payment. Principal and interest today compared with principal and interest on the larger loan at the rate you expect later.
- Extra paid over the life of the loan. The added down payment plus every higher monthly payment across the full loan term.
- Equity you would build by buying now. Appreciation plus the principal you would pay down during the months you would otherwise wait.
What the Calculator Leaves Out
To keep the comparison clear, the calculator does not count rent you pay while waiting, property taxes, insurance, closing costs, refinancing or what your down payment could earn in savings. Rent usually makes waiting cost more, while a lower rate or a refinance can make it cost less. For current average mortgage rates, see the Freddie Mac weekly rate survey, and for a plain-English walk through the loan process, the CFPB's Buying a House guide is a good start.
Why Today's Market Can Favor Ready Buyers
Higher rates have kept many buyers on the sidelines, and less competition can mean more negotiating room on price, inspection repairs, closing costs and even a seller-paid rate buydown. That room tends to shrink when more buyers come back. Read more in our guide to buying a house in Eau Claire right now, browse Eau Claire WI homes for sale, or check the latest market snapshot. Selling a home first? The seller net sheet calculator shows what you could walk away with.
Cost of Waiting to Buy a Home FAQ
Is it better to wait for mortgage rates to drop before buying?
It depends on how much prices rise while you wait and how far rates actually fall. A lower rate on a higher price can still cost more over the life of the loan. Enter a lower future rate in the calculator to find the break-even point for your situation.
What appreciation rate should I use?
Nobody can predict home prices. Eau Claire's median sale price was roughly flat year over year in spring 2026, while longer-term growth has been much stronger, so try a few rates, including 0% to 2%, to see the range of outcomes.
Does the calculator include taxes and insurance?
No. The payments shown are principal and interest only. Property taxes, homeowners insurance, mortgage insurance and HOA dues would be added to your actual payment.
Where should I get a real interest rate?
From a licensed mortgage lender. Your rate depends on your credit, down payment, loan program and the day you lock. We are happy to introduce you to local lenders we work with.
Not sure which scenario fits you? Reach out to AJ for a no-pressure conversation. Which matters more to you right now, the monthly payment or the purchase price?
Disclosures
This cost of waiting calculator is an educational tool for general information only. It is not an offer to lend, a loan approval, a pre-qualification, a rate quote or a commitment of any kind. Summit Real Estate Group, AJ Minaker and REAL Broker, LLC are not mortgage lenders and do not make loans.
The default figures, including interest rates, home price, down payment and appreciation, are examples chosen for illustration. They are not predictions, current market rates or terms available to you. The annual percentage rate (APR) is not shown. Actual rates, payments, APR, down payment requirements and loan terms depend on your credit, income, loan program, property and lender, and can change at any time.
Results are estimates based only on the numbers you enter. They assume a fixed-rate loan, the home appreciates and rates move as entered, and payments of principal and interest only, not taxes, insurance, mortgage insurance, HOA dues or closing costs. Results do not account for rent paid while waiting, refinancing, or investment return on your down payment. Home values and interest rates can rise or fall, and no future value or rate is guaranteed.
Nothing on this page is financial, legal or tax advice. Talk with a licensed mortgage loan originator about loan options and a tax professional about tax questions. The numbers you enter stay in your browser and are not saved or sent to us.
AJ Minaker, License ID 93628. Summit Real Estate Group | REAL Broker. Real estate brokerage services are provided by REAL Broker, LLC. Equal Housing Opportunity.